The medical bill arrives after your appointment, and the amount is higher than you expected. Before looking at personal loans for medical expenses, find out which charges you actually owe. An insurance claim may still be processing, a payment may be missing from the statement, or the provider may offer assistance. We encourage you to work from a confirmed balance rather than borrow against an estimate that might change. A few calls now can leave you with less to repay later.
Confirm What You Actually Owe
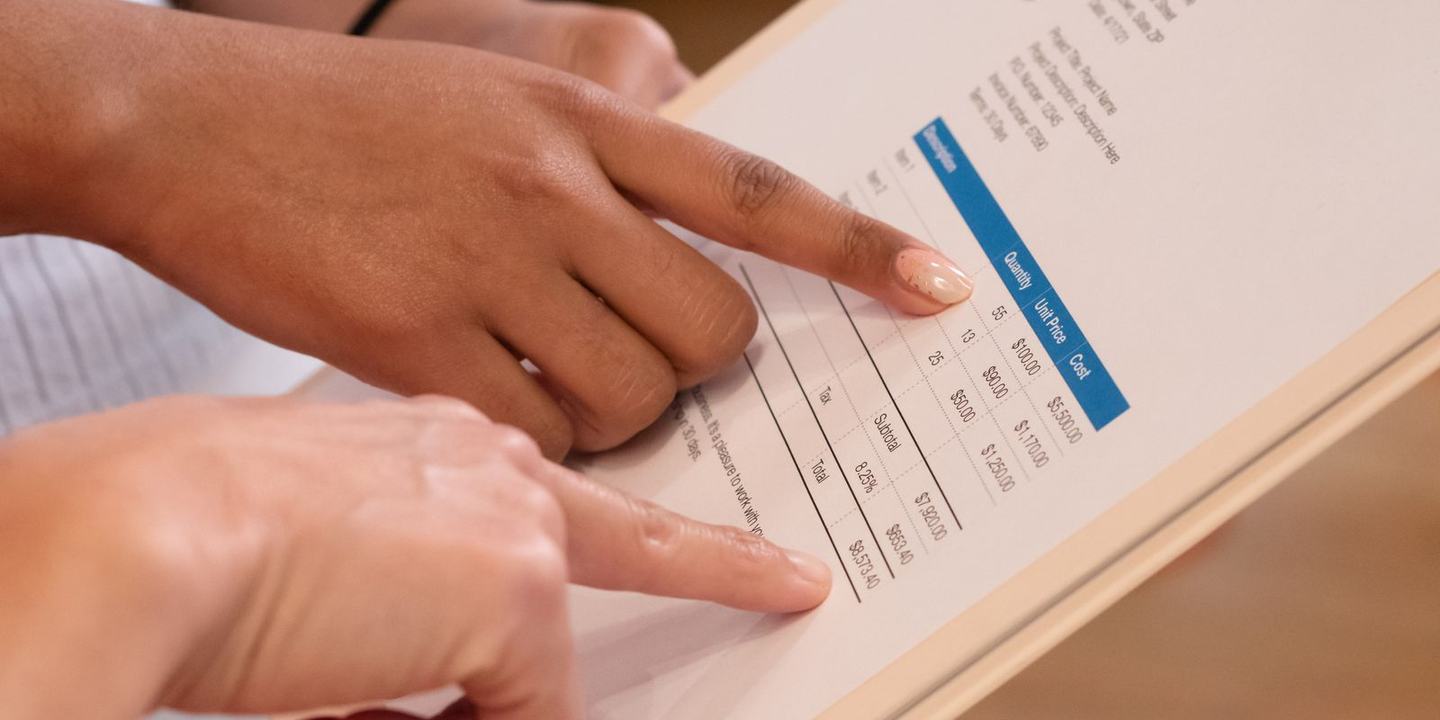
If you have insurance, compare the bill with your Explanation of Benefits (EOB). Your insurer sends the EOB to explain how it processed a claim; the EOB itself is not a request for payment. Match the service dates, provider names, adjustments, and patient responsibility against the actual bill. An appointment involving several clinicians may generate separate statements, so check each one rather than assuming the first invoice covers everything.
Ask the billing office for an itemized statement if a charge is unfamiliar. Look for duplicate services, amounts already paid, and whether insurance information was submitted correctly. If a claim is still pending, ask when the provider expects a final patient balance. Record the name of the person you speak with and what they agree to investigate. Keep copies of revised statements in case the balance changes.
Ask About Assistance Before Adding Debt
Before committing to a lender, review the amount you owe and ask the provider about financial assistance. Some hospitals have charity-care programs that reduce eligible patients' charges. Eligibility depends on the provider and your circumstances, and you may need to submit income documents. Ask for the application and a clear explanation of any deadline rather than assuming your bill automatically qualifies.
A billing office may also discuss a payment plan, including whether it charges interest or administrative fees. Get the schedule in writing. Ask when the first payment starts, what happens if you miss one, and whether the account could go to collections during an agreed plan. Compare that answer with the cost of outside borrowing before deciding.
Compare the Full Loan Cost With Your Budget
Once the provider confirms your balance, separate the amount needed for care from the price of financing it. A monthly payment that fits this paycheck can still be costly over a long term. Check the annual percentage rate (APR), any origination fee, the number of payments, and the total repayment shown in the lender's disclosures. If a fee comes out of the loan proceeds, the cash available for the bill may be smaller than the loan amount.
Use a simple worksheet with figures from your own statements and written offer. Put these four entries side by side before you sign:
| Figure to confirm | Where to get it |
|---|---|
| Remaining patient balance | Corrected provider statement |
| Amount you would finance | Proposed loan agreement |
| Total repayment including fees | Lender disclosures and payment schedule |
| Monthly payment | Written terms and household budget |
Check the payment against rent, groceries, transportation, and existing obligations, using the month with the tightest cash flow. Leave room for follow-up visits or prescriptions if your care team expects them. Paying a bill with credit does not erase the obligation; it changes whom you owe and when.
Know When to Stop and Ask More Questions
Pause if your statement does not match the insurance paperwork, the provider has not decided an assistance application, or the proposed payment would squeeze essential spending. Ask the billing office, "Is this the final amount I owe?" Ask your insurer, "Is any claim or appeal still open?" Ask the lender, "What will I repay in total, including every fee?" The answers should agree with the documents in front of you.
Some care starts with testing, and planning for medical investigations may involve separate bills before anyone knows the full treatment cost. Avoid treating a tentative figure as your final financing target. We want you to have enough information to choose a manageable next step, including the option of waiting for a corrected bill.